Key takeaways
- Paying a worker on a 1099 is a tax decision. It does not make them a subcontractor, and carriers do not treat it as one.
- A true subcontractor carries their own general liability, workers compensation, and often commercial auto. Every policy they don't carry is one your business absorbs.
- If a crew works only for you, a carrier will most likely treat them as your employee, including for injuries on the job.
- Texas makes workers compensation optional for most private employers, which is exactly why this question gets blurry here and why it lands in your rate.
| How you pay them | What they carry | Whose risk it is |
|---|---|---|
| W-2 employee | Your general liability, your workers comp | Yours, fully |
| 1099, works only for you | Usually nothing of their own | Yours. A carrier will most likely treat them as an employee |
| 1099 true subcontractor | Their own GL, workers comp, often commercial auto | Theirs, to the extent they actually carry it |
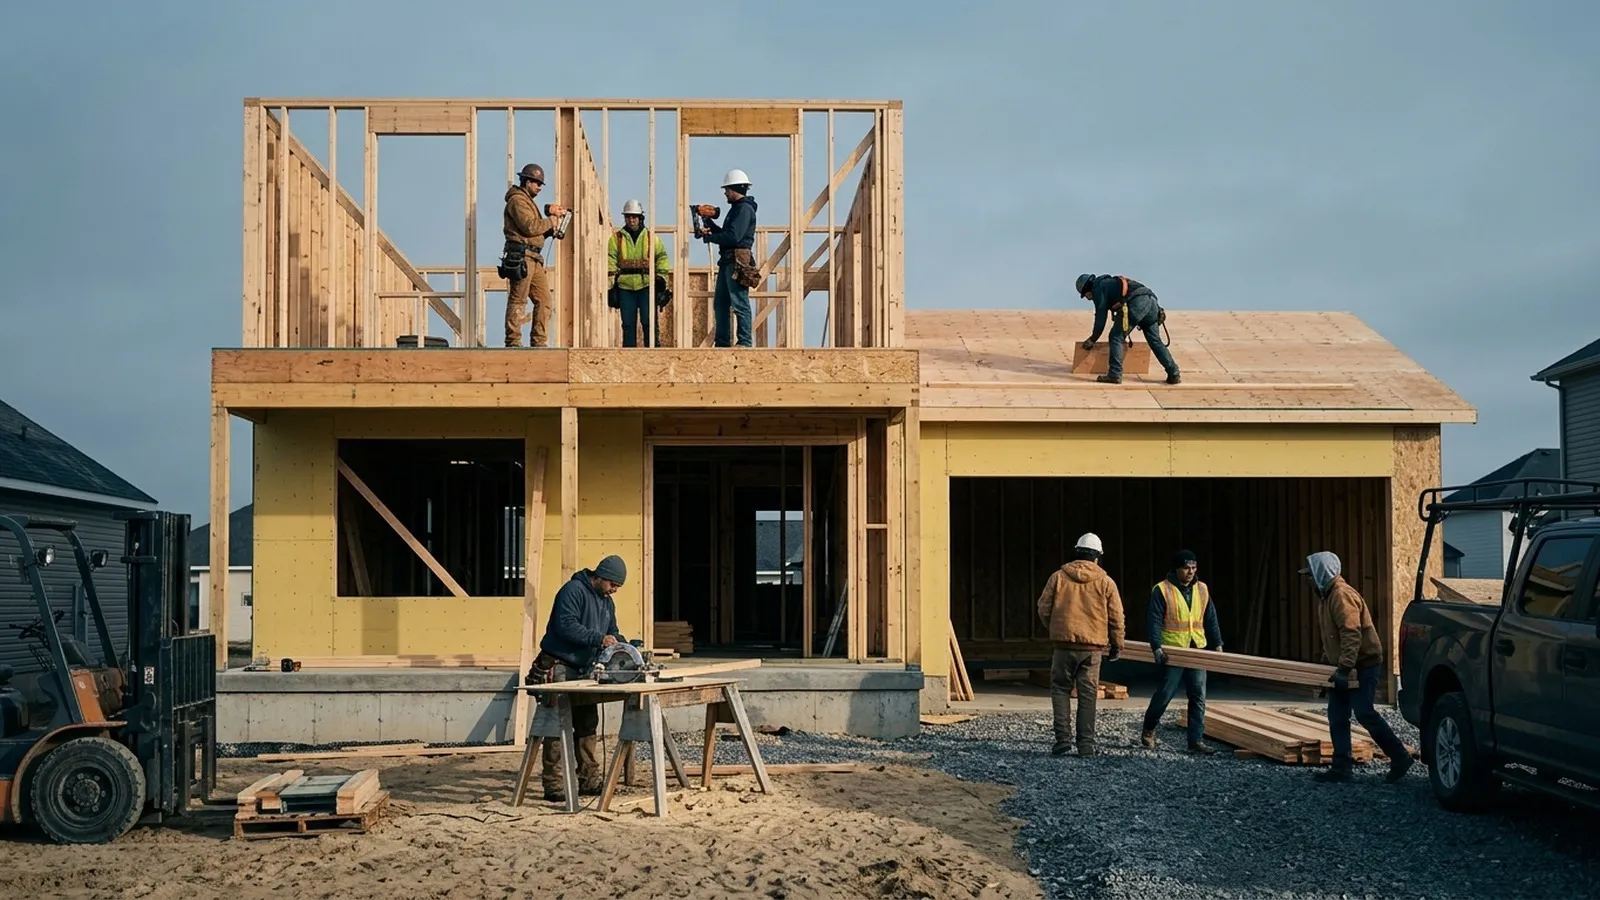
Three workers who can look identical on a job site
Self-performing and subcontracting are two different businesses
Some contractors self-perform. Their own people are the ones on the project putting the work in place, whether those people are paid W-2 or 1099.
Other contractors subcontract out a large portion of their scope.
Both are legitimate ways to run a business. But if you subcontract, the question a carrier is going to care about is whether those subs carry their own insurance.
If they do, those are true subcontractors, and you as the main contractor aren’t assuming the risk for their performance. If they put work in place that doesn’t satisfy your client, their insurance would be the one to respond.
If they don’t carry it, you’re the one assuming that responsibility. And that shows up when your policy is rated.
Why a 1099 is a tax decision, not a risk decision
Employees are typically staff that work only for you and you pay them W-2. That means you’re not only withholding their taxes and Social Security, you’re also reporting and taking responsibility for paying all of that to the state.
Sometimes you have people who work only for you, but you pay them 1099 because you don’t want to be responsible for paying those taxes. That does not mean they are a subcontractor. It just means you’re paying them on a 1099.
A true subcontractor is someone you pay on a 1099, but who carries their own insurance. Their own general liability to cover their completed services and operations. Their own workers compensation to cover bodily injury to their employees. Perhaps their own commercial auto, in case they hit someone driving to or from a project and there’s property damage or an injury.
Not every sub will carry all three of those policies. But the more of it they carry, the less of their risk is sitting on you.
All three of those workers might look identical on your job site. Only one of them is actually holding their own risk.
The question I always ask: who do they work for besides you?
The answer changes everything.
If a subcontracting team does not work for anyone else, if they only work for your company, they are most definitely going to be considered your employee.
Which means you’re not just responsible for the work they put in place. You’re also responsible for their injuries if they get hurt on a job.
That second part is the one that catches people. When business owners think about subcontractor risk, they’re usually picturing faulty work. The injury side is sitting right next to it.
So take a minute and go through your list. For each crew you pay on a 1099, answer two separate questions: do they work for anyone besides you, and do they carry their own coverage?
Why this is blurrier in Texas than in most states
Texas does not require most private employers to carry workers compensation. That’s unusual, and it’s the reason this classification question comes up more here than it does elsewhere.
When comp is optional, more crews go without it. A sub who would carry workers comp as a matter of course in another state may carry nothing here, and still call themselves a subcontractor. From the outside, the arrangement looks the same. The risk position is completely different.
It also means that when a worker does get hurt, there’s often no comp policy standing between the injury and your business. Waiving workers comp in Texas doesn’t just save a premium. It removes the legal protections that come with carrying it, and leaves injury claims to be argued without those limits.
That is why a DFW contractor and a contractor in a mandatory-comp state can present the same scope of work and be rated very differently.
What a carrier is actually looking at
- What's your full scope of service?
- How much revenue is being generated from each of those scopes?
- What portion of that work is self-performed versus how much is truly subcontracted out?
- Do you have a subcontractor agreement in place, and what's in it?
That last one matters more than most contractors expect. Specifically, whether the agreement contains a hold harmless clause. In plain language, that clause means your subcontractor will not sue you for damages if they cause injuries or cause faulty work while performing their scope of service on your project.
It’s one paragraph. It’s also one of the things a carrier weighs when deciding what kind of risk your company represents.
That’s why comparing premiums with another contractor almost never works. When you’re talking to peers, you’re not getting an apples-to-apples comparison unless you know every detail that went into how their policy was rated. And you almost never do.
Frequently asked questions
Not sure which category your crews fall into?