Key takeaways
- If a vehicle is titled in your personal name but used for business, an attorney can name your personal assets alongside your business assets in the same claim.
- A leaseback agreement leases that personally titled vehicle to the business and is what walls off the liability.
- Carrying workers compensation lowers what you pay for commercial auto, because it moves employee injury costs off the auto carrier.
- Pull a motor vehicle report before you hand an employee the keys, or you'll learn about their driving history when your renewal comes back.
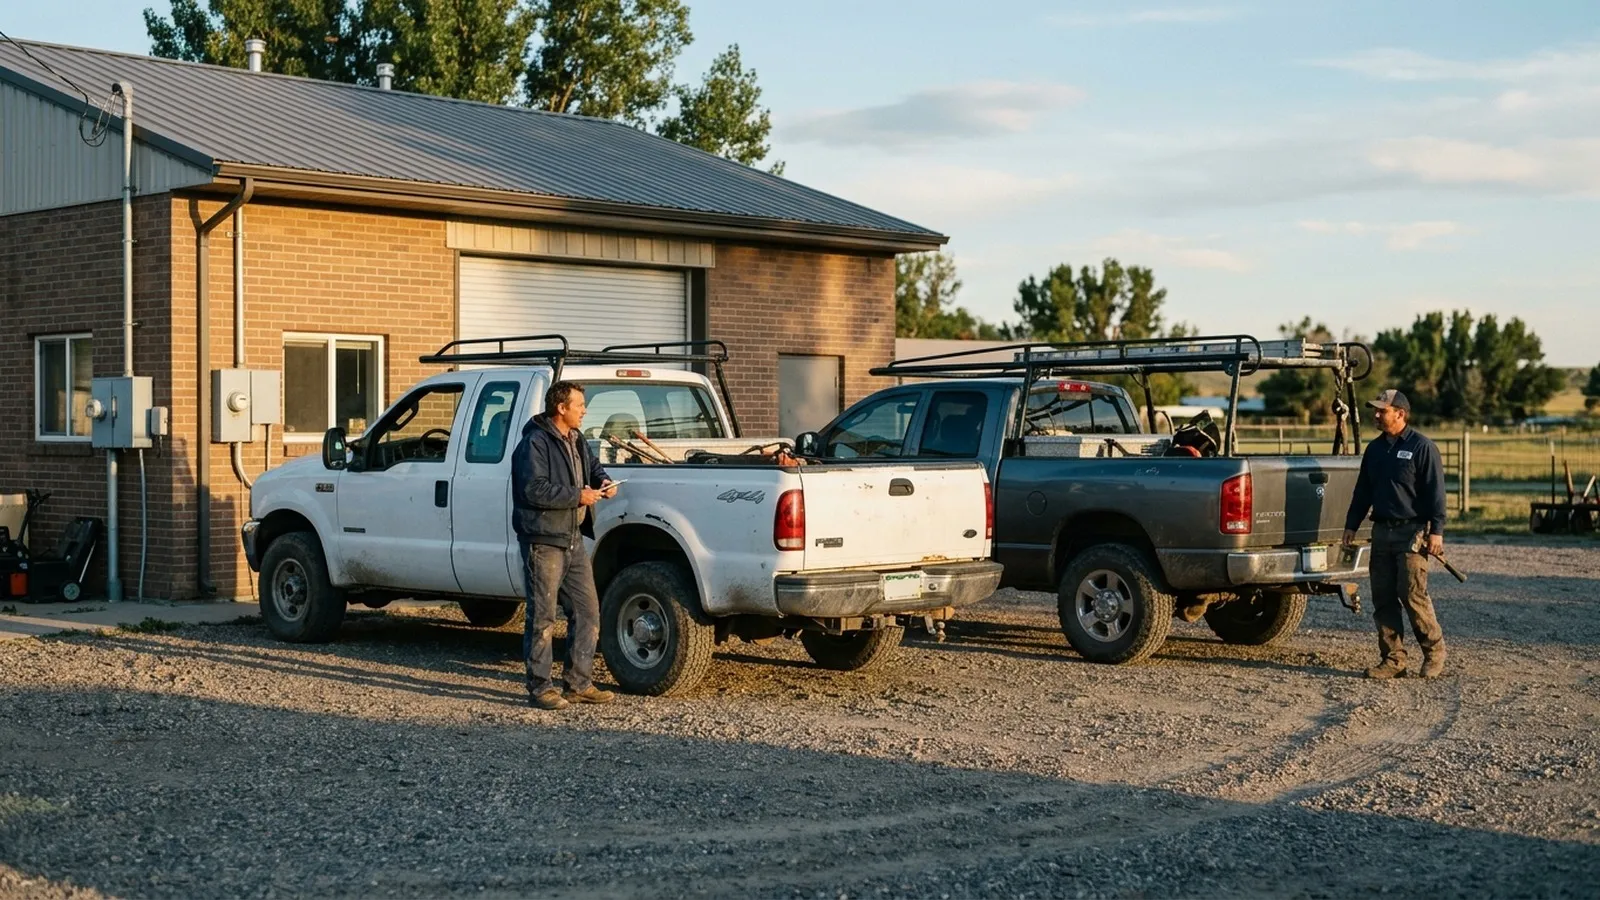
A lot of small business owners, solopreneurs, and contract workers use their own vehicle for business. Running errands. Driving to sales meetings. Realtors across DFW taking clients out to view homes.
Most of them are writing the mileage off on their taxes. Far fewer have looked at what that does to their liability.
It feels like a non-issue, and for most people it stays one right up until it doesn’t.
| Your setup | What’s exposed | What closes the gap |
|---|---|---|
| Personal vehicle, personal use only | Nothing business related | Nothing needed |
| Personal vehicle used for business, personal policy only | A business-use claim may not be covered at all | Some form of commercial auto policy |
| Personally titled, commercial auto in place, no leaseback | Your personal assets can be named alongside the business | Leaseback agreement |
| Titled to the company or LLC, commercial auto in place | Business assets only | Right structure already |
Where your vehicle actually sits
The exposure most people don't see
When you use a vehicle for business, you’re assuming responsibility for the people in it and their injuries, whether they’re employees or clients.
And if you’re driving a vehicle titled in your personal name, meaning you purchased it as an individual and it’s tied to your person and not to the company or the LLC, then you’ve opened up the opportunity for an attorney representing a plaintiff for bodily injury to reach your personal assets as well as your business assets.
Both are going to be named in the claim or lawsuit.
That’s the piece people miss. The write-off is a tax decision. The titling is a liability decision. They are not the same decision, and making the first one without addressing the second is exactly where the exposure lives.
How to wall off that liability
There are ways to close this.
If you’re a business owner or entrepreneur using your own vehicle for business, especially if you’re writing it off on your taxes, you should have some type of commercial auto policy.
And there’s a second piece that gets skipped constantly. If you have a vehicle in your personal name and you have a commercial auto policy, you need what’s called a leaseback agreement. That’s a document where you, as the individual, sign over or lease that vehicle to the business.
The purpose of that agreement is to create a wall of liability, so that you as a person aren’t implicated in a potential claim or lawsuit alongside the business.
Whether that structure fits your situation depends on your entity, your titling, and how the vehicle is actually being used. That’s a conversation worth having with your agent and your accountant together, rather than assuming the policy alone has you covered.
The write-off is a tax decision. The titling is a liability decision. They are not the same decision.
The underwriting question that surprises everyone
When I’m writing a commercial auto policy for a carrier, one of the underwriting questions is whether the drivers are covered for workers compensation insurance elsewhere.
People always ask what comp has to do with their trucks.
Here’s why it matters. If there’s bodily injury to that employee, or to the owner, while they’re driving that vehicle, the auto carrier is now on the hook for all of it. The hospitalization, the emergency room trip, the injury costs. That’s in addition to the physical damage to the vehicles, and in addition to any bodily injury or property damage to other people and other people’s property.
Carriers naturally don’t want to be paying those costs when a workers comp policy would pay for them instead. So it greatly impacts the rate.
If I have two clients who both carry commercial auto, and one carries workers comp and one doesn’t, I can almost guarantee you the one without comp is going to be at a higher rate on that auto policy.
This lands harder in Texas than in most states, because Texas doesn’t require most private employers to carry workers compensation. A lot of small operations here skip it to save the premium, then find that the savings partially reappear as a higher commercial auto rate, and that injury costs have nowhere else to go.
Before you hand anyone the keys
One more, and it’s cheap to do.
If you’re hiring employees who are going to be driving company vehicles, you need to run a motor vehicle report on them first.
You want to confirm they have a clean driving record, and you want to see what their claims history looks like.
If you don’t, that’s going to significantly impact the premium for your commercial auto, and you’ll end up learning about a driver’s history at the worst possible time, which is after the rate comes back or after a loss.
The short version
- You use a personally titled vehicle for business
- You write vehicle expenses off on your taxes
- You have a commercial auto policy on a personally titled vehicle and no leaseback agreement
- You have employees driving company vehicles and have never pulled a motor vehicle report
- You carry commercial auto but not workers comp
Frequently asked questions
Not sure whether your vehicle setup actually protects you?